Opening a Swiss bank account as a foreigner is still possible in 2026 — but the process looks nothing like what most guides describe. I am Asel Mamytova, Managing Director of BMA Business Solutions in Chur, Switzerland, and I have spent over 15 years helping international clients navigate this system. The short answer: Swiss banks will accept you if your financial story is clean, consistent, and professionally presented. The longer answer involves compliance layers most applicants never see coming.
This guide shares what I have personally observed — not theory, but patterns from real application files, real compliance conversations, and real rejections that could have been prevented.
Looking for Direct Executive Introduction Rather Than a DIY Application?
If you are an entrepreneur, family office, or high-net-worth individual deploying k+ and require pre-cleared access without compliance rejection risk, explore our non-resident bank account introduction service. For individuals navigating the legal requirements independently, this comprehensive technical guide explains the exact Swiss regulatory framework.
What Has Actually Changed for Foreign Clients in 2026
Swiss banking has been tightening its onboarding criteria steadily since 2017, when the Common Reporting Standard went live. By 2026, most Swiss banks have moved so far into wealth management and compliance-intensive private banking that classic retail onboarding for non-residents has nearly disappeared. UBS stopped accepting new retail non-resident clients years ago. PostFinance restricts non-residents significantly. The cantonal banks largely serve Swiss residents.
Swiss anti-money laundering regulations enforce strict statutory declarations; verify all required paperwork under Form A beneficial ownership and CDB 20 rules.
What remains for foreign non-residents is a tiered market: fintech and online trading platforms at the entry level, mid-market private banks requiring meaningful deposits, and elite private banking for high-net-worth clients. Each tier has different compliance expectations. Knowing which tier fits your profile is the first real decision.
In my practice, the single most common mistake is a client approaching a Tier 1 private bank with a CHF 200,000 deposit and a complex corporate structure. They are not being rejected because they are foreign. They are being rejected because they do not fit the bank’s minimum relationship model — and their file does not justify the compliance cost of onboarding them. Understanding this distinction changes everything.
Realistic Minimum Deposits for Non-Residents: The Real Numbers
Published minimums and practical minimums are two very different things for foreign non-residents. Banks rarely advertise their real thresholds for non-residents from high-compliance jurisdictions. Here is what I see in actual practice in 2026, broken down by bank category.
Compare statutory state-backed guarantees versus private liquidity ratios in our detailed cantonal banks vs private banks safety rating audit.
Horizontal bar chart showing minimum deposit ranges for non-resident foreigners across five Swiss banking categories: fintech/neobanks CHF 0–10,000; online trading banks CHF 5,000–50,000; universal banks CHF 50,000–200,000; mid-market private banks CHF 500,000–1 million; elite private banks CHF 1 million to 10 million plus.
| Bank Category | Practical Minimum (Non-Resident) | Examples | Remote Opening? | Notes |
|---|---|---|---|---|
| Fintech / Neobanks | CHF 0 – 10,000 | Dukascopy, Relio, Yuh | Yes (full digital KYC) | Limited services; not full private banking; no wealth management |
| Online Trading Banks | CHF 5,000 – 50,000 | Swissquote, CIM Banque | Yes (video ID) | Trading-focused; CHF/multi-currency; suitable for active investors |
| Universal / Retail Banks | CHF 50,000 – 200,000 | UBS (limited), some cantonal banks | Rarely for non-EU | Very restricted for non-residents without Swiss ties; residence permit often required |
| Mid-Market Private Banks | CHF 500,000 – CHF 1,000,000 | CBH, BCP, Banque SYZ, EFG, VP Bank | Partial (one visit typical) | Most accessible tier for non-EU HNWIs with clean profiles; EDD applies |
| Elite Private Banks | CHF 1,000,000 – CHF 10,000,000+ | Julius Baer, Pictet, Lombard Odier, Rothschild | No (in-person mandatory) | Julius Baer tightened minimum in Dec 2025; Pictet manages €788B AUM; bespoke relationships only |
One number I want to flag specifically: the CHF 500,000 to CHF 1,000,000 gap. At my firm, I describe this as the “compliance gap.” You are too large for online trading platforms that process you automatically, and too small for the mid-market private banks that justify their enhanced due diligence costs at CHF 500,000 and above. If you are sitting between CHF 200,000 and CHF 500,000 as a non-EU, non-Swiss client, your banking options in Switzerland are genuinely limited. This is not widely discussed. It should be.
For clients who want to explore the full range of deposit structures across multiple Swiss institutions, our Swiss bank account minimum balance guide goes deeper into each tier.
What Compliance Due Diligence Actually Means — And How Banks Do It
Every foreign applicant hears the phrase “due diligence.” Almost none of them understand what the bank is actually doing during those four to eight weeks. Let me explain it plainly, because this knowledge directly changes how you prepare your application.
Clients evaluating European wealth hubs outside the Alpine confederation should examine our banking in the Principality of Monaco guide.
Compliance due diligence in Swiss banking has three formal layers under FINMA’s risk-based framework: standard KYC, Customer Due Diligence (CDD), and Enhanced Due Diligence (EDD). Which tier you fall into depends on your risk profile at the point of application.
Here is what most applicants miss: the bank is not trying to catch you. They are trying to document that they tried. Every step of their due diligence creates a paper trail that protects them in a FINMA audit. Your job is to make their documentation job easy. When you submit a clean, consistent file with no unexplained gaps, their paper trail writes itself. When your file has inconsistencies, they have to investigate — and that investigation is expensive, slow, and often ends in rejection.
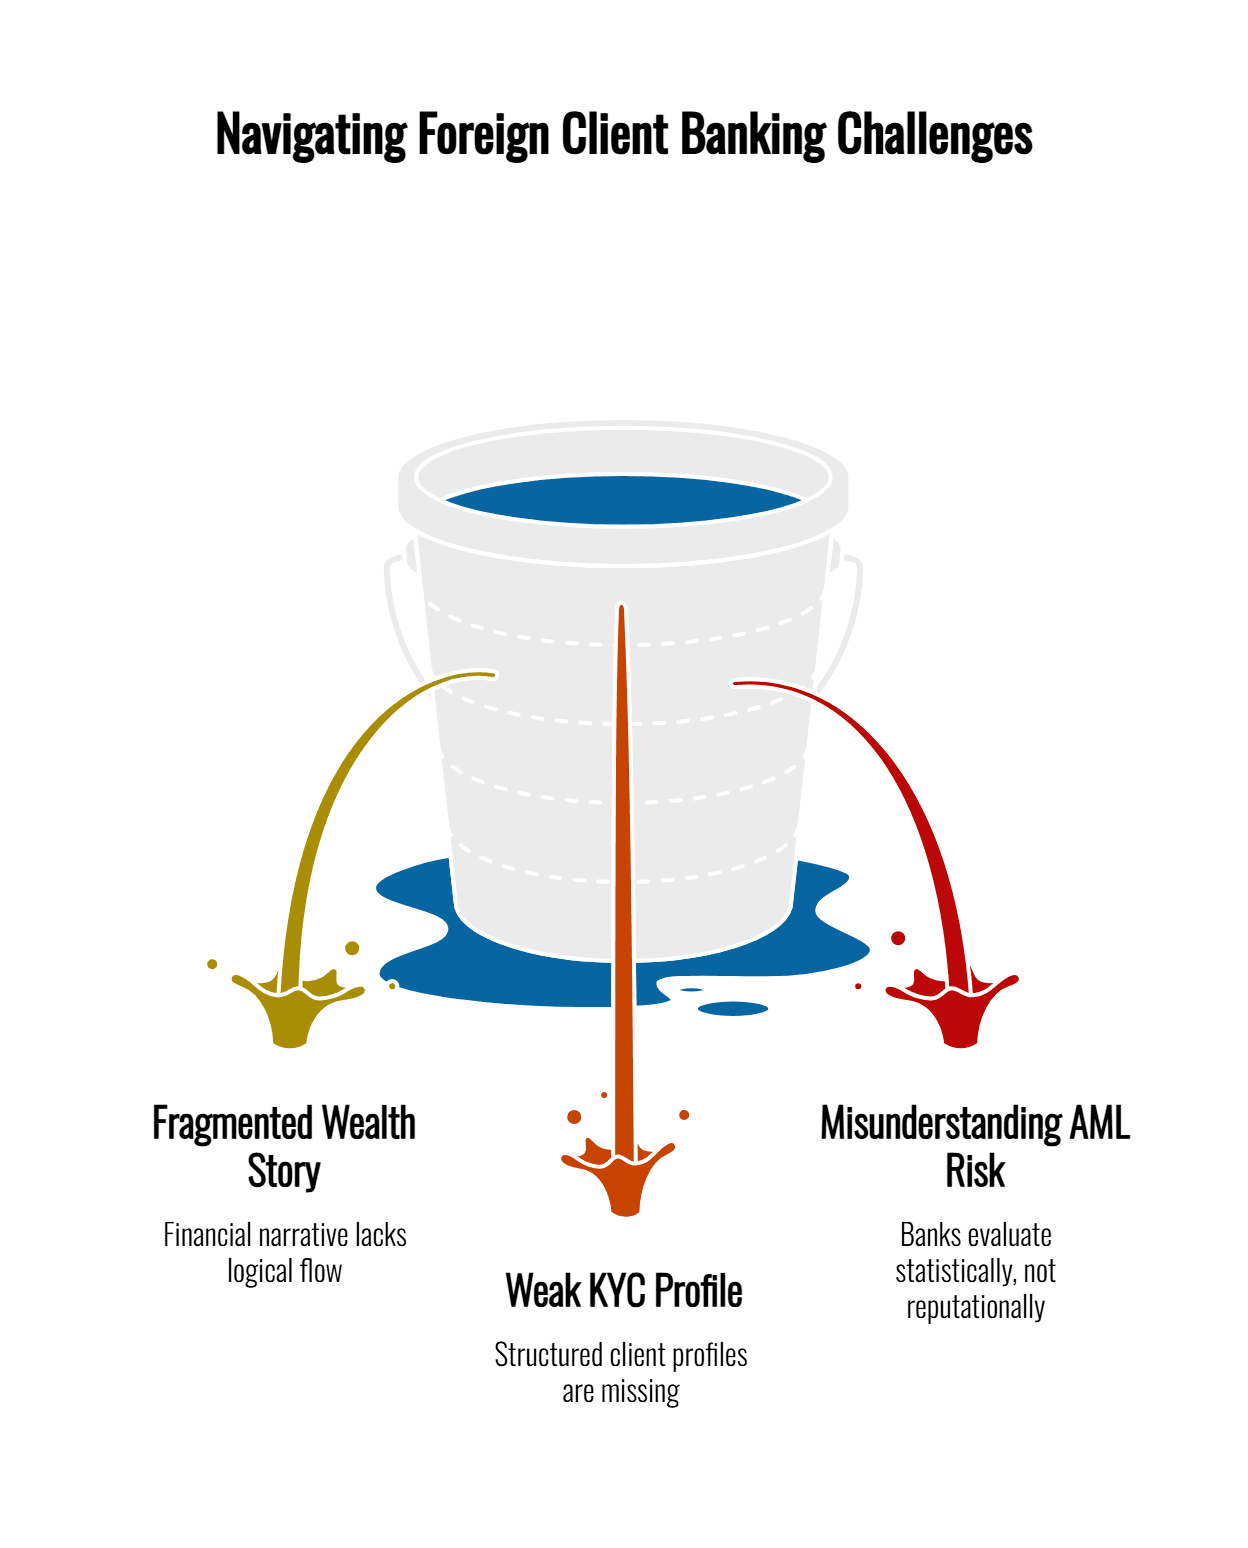
The DIY vs Introduced Application Path: Why 75%+ of Direct Submissions Fail
Non-residents opening a Swiss bank account face two fundamentally different procedural routes: the Self-Directed (DIY) Path and the Professional Fiduciary Introduction Path. Understanding the operational reality of both options is critical to protecting your banking reputation:
When initiating direct contact with relationship managers, follow our protocol on how to identify accredited Swiss wealth managers.
| Assessment Dimension | Self-Directed (DIY) Application | Professional Fiduciary Introduction |
|---|---|---|
| Intake & First Point of Contact | Junior triage intake clerks or generic online form. Evaluators are incentivized to decline ambiguous files to minimize desk risk. | Executive Managing Director or Desk Head specializing in the applicant’s region. The file enters directly at decision-maker level. |
| Pre-Clearance Protocol | None. Applicant submits unvetted documents blindly into compliance queues. Any flaw results in outright rejection. | Anonymized pre-clearance with compliance and legal officers before any formal submission. 100% certainty of appetite before filing. |
| Source of Wealth Presentation | Fragmented, raw documents (bank statements, contracts) submitted without an executive fiduciary memorandum. | Structured Wealth Narrative & Document Index conforming directly to FINMA and CDB 20 evidentiary requirements. |
| Acceptance Rate (Non-Residents) | ~15%–25% for non-residents without pre-existing Swiss substance. High risk of file abandonment. | 95%+ on pre-vetted client files accepted into mandate. |
| Onboarding Timeline | 8–16 weeks (frequent rounds of formal queries, requests for clarification, and delays). | 2–4 weeks (expedited due diligence review with pre-aligned documentation). |
The Regulatory Core: CDB 20 Rules and Beneficial Ownership Declarations
All Swiss banks operate under the CDB 20 (Agreement on the Swiss Banks’ Code of Conduct with Regard to the Exercise of Due Diligence / VSB 2020). Recognized by the Swiss Financial Market Supervisory Authority (FINMA), CDB 20 legally requires banks to verify the identity of the contracting partner and to establish the identity of the ultimate beneficial owner of the assets with absolute certainty.
Form A: Declaration of the Beneficial Owner
When Mandated: Form A is mandatory whenever an account is opened by a natural person holding assets on behalf of another, an operating company with complex shareholding, an offshore holding company, or an entity without active commercial operations.
The Legal Test: Form A requires the explicit declaration of the natural person (first and last name, date of birth, nationality, residential address) who is the true economic owner of the funds.
Criminal Penalties (Art. 251 StGB): Signing a false Form A is not merely an administrative infraction. Under Article 251 of the Swiss Criminal Code (Schweizerisches Strafgesetzbuch), intentionally providing false statements on Form A constitutes criminal document forgery (Urkundenfälschung), punishable by up to five years imprisonment or monetary penalty.
Form K: Identification of the Controlling Person
When Mandated: Form K is required under CDB 20 Art. 45 for unlisted operating commercial companies, industrial corporations, and family foundations where no single natural person holds 25% or more of the capital or voting rights.
The Controlling Person Standard: If ownership is widely dispersed or structured through institutional vehicles, Form K identifies the individual who exercises ultimate managerial control (such as the Managing Director, CEO, or Chairman of the Board of Directors).
Trusts & Foundations: Discretionary trusts and foundations trigger specialized beneficial ownership documentation (Form T or Form S) identifying settlors, protectors, trustees, and named beneficiaries.
Source of Wealth (SoW) vs. Source of Funds (SoF): The Evidentiary Matrix
The single most frequent cause of Swiss bank account rejection is conflating Source of Funds (SoF) with Source of Wealth (SoW). Compliance officers evaluate two entirely distinct questions:
| Wealth Category | Source of Wealth (Lifetime Accumulation) | Source of Funds (Specific Wire Deposit) | Common Rejection Triggers |
|---|---|---|---|
| Business Ownership / Company Sale | Share purchase agreement (SPA), audited annual financial statements (5–10 years), commercial registry extracts, dividend distribution tax vouchers. | Escrow release confirmation, corporate bank statement showing net proceeds, wire confirmation directly from buyer/escrow agent. | Funds transferred through an intermediary third-party account rather than directly from the seller’s verified account. |
| Executive Compensation & Bonus | Employment agreements, multi-year filed personal tax returns, stock option vest agreements, audited remuneration statements. | Recent salary slips, broker payout receipts, bank statements showing salary accumulation over 12–24 months. | Tax declarations showing income insufficient to explain the quantum of accumulated liquid assets. |
| Real Estate & Capital Assets | Historical deed of purchase, land registry extract, capital gains tax clearance certificate, proof of mortgage redemption. | Notarized deed of sale, notary closing settlement statement, bank statement showing credit from notary escrow account. | Unexplained cash transactions or private unnotarized promissory notes. |
| Inheritance & Estate Wealth | Notarized will, probate court certificate, official inheritance tax assessment and receipt of payment, distribution agreement. | Estate executor bank transfer advice, bank statements showing distribution from estate account into beneficiary’s name. | Informal family cash distributions lacking official probate court or tax authority validation. |
Remote Video KYC vs In-Person Onboarding: FINMA Circular 2016/7 Rules
Under FINMA Circular 2016/7 (Video and Online Identification), Swiss financial institutions are legally authorized to onboard foreign clients without requiring a physical trip to Switzerland. However, whether your file can be processed purely digitally depends strictly on your jurisdictional profile and document security features:
- Digital Video KYC Eligibility: Applicants holding biometric passports issued by EEA, UK, Swiss, US, Canadian, or selected low-risk jurisdictions with machine-readable zones (MRZ) and cryptographic security features can complete video onboarding via encrypted video call with an accredited identity provider.
- Apostille & Certified Documentation: For jurisdictions outside the automated video KYC corridor, Swiss banks require verified certified true copies of passports and proof of address bearing a Hague Apostille (Convention de La Haye du 5 octobre 1961) or diplomatic consular legalization.
- Mandatory In-Person Meetings: When an account involves complex offshore operating entities, politically exposed persons (PEPs), assets exceeding CHF 5M+, or high-risk jurisdictions, Swiss private banks mandate an in-person meeting with the relationship manager—either at the bank’s headquarters in Zurich, Geneva, Lugano, or Chur, or at one of their authorized international representative offices.
Enhanced Due Diligence (EDD) is triggered automatically in certain situations: nationality from a high-risk jurisdiction, unexplained international fund flows, politically exposed person (PEP) classification, or assets in excess of CHF 1 million without a clear verifiable source. EDD involves deeper background checks, third-party verification of business claims, and in many cases a face-to-face meeting with a senior relationship manager.
From my own files: I once worked with a client who had 12 years of audited financial statements, clean tax records across three jurisdictions, and a completely straightforward business history. His application still took 11 weeks because his country of incorporation was flagged as high-risk. The documents were perfect. The jurisdiction did the damage. This is why pre-assessment matters more than document quality alone.
Nationalities That Face Specific Difficulties — And Exactly Why
This section is the one most guides skip. I am going to be direct, because this is information that genuinely helps people plan correctly.
United States Citizens: The FATCA Problem
HIGH DIFFICULTY
American citizens face the most structurally complex path to Swiss banking, regardless of their wealth level. The reason is FATCA — the Foreign Account Tax Compliance Act. FATCA requires every Swiss bank to identify US person account holders and report their account details directly to the IRS. This creates an ongoing compliance and reporting obligation that costs Swiss banks significant money every year.
Many Swiss private banks simply refuse US clients as a matter of policy. Not because Americans are high-risk — but because the compliance infrastructure to service them properly is expensive to build and maintain. Julius Baer, Pictet, and Lombard Odier do accept US clients, but only at the private banking tier with dedicated US compliance teams. Additionally, US clients must file FBAR (Report of Foreign Bank and Financial Accounts) annually with FinCEN and report the account on their US tax return. Swiss banks require Americans to acknowledge FATCA reporting explicitly during onboarding. The practical result: US clients have fewer Swiss bank options, face longer onboarding timelines, and should expect additional documentation requirements around their US tax compliance history.
Canadian Citizens: The Underappreciated Complexity
ELEVATED DIFFICULTY
Canada participates in CRS and has its own robust anti-money laundering framework (FINTRAC). Canadian clients are generally not considered high-risk jurisdictions — but Swiss banks approach them with caution for two reasons. First, there is a strong US-Canada financial relationship, and Swiss banks that refused US clients often implemented similar policies for Canadians due to operational overlap. Second, the FINTRAC reporting obligations for Canadian-sourced funds require Swiss banks to carefully verify that Canadian tax compliance is in order — particularly for clients with offshore corporate structures or multi-jurisdictional income. In practice, Canadians can open Swiss accounts, but they need to demonstrate clean Canadian tax history and clear documentation of their banking relationship purpose.
Chinese Citizens: Capital Controls and AML Tier
HIGH DIFFICULTY
Chinese nationals face a layered set of challenges that go beyond standard compliance. First, China’s State Administration of Foreign Exchange (SAFE) imposes capital controls that limit individual annual outflows to USD 50,000 equivalent. Any Chinese client with assets significantly exceeding this in a Swiss account will be asked to explain how those assets left China legally. This is not a disqualifier — but the documentation burden is substantial. Second, China’s CPI score and FATF risk classification place Chinese clients in an elevated AML risk tier, triggering EDD automatically at most Swiss private banks. Third, there is elevated concern about PEP exposure — given the prevalence of Communist Party membership in senior business roles, Swiss compliance teams scrutinize beneficial ownership structures carefully. Chinese clients can absolutely open Swiss accounts, particularly at mid-market private banks. But the process is longer, the documentation requirements are higher, and the minimum deposit expectations are typically at the upper end of the bank’s stated threshold.
Japanese Citizens: A Different Kind of Complexity
MODERATE-ELEVATED DIFFICULTY
Japan is a G7 country and participates fully in CRS. Japanese clients are not considered high-risk jurisdictions. The difficulty is more operational. Japanese wealth is often structured in yen-denominated assets, domestic real estate, and corporate shareholdings that are less familiar to Swiss compliance teams than EUR or USD-denominated portfolios. Source of wealth documentation frequently requires translation and notarization from Japanese into languages Swiss banks can process. Additionally, there are JFSA (Japan Financial Services Agency) reporting requirements that intersect with Swiss banking disclosures, creating a documentation pathway that takes longer to complete. Language barriers add to the timeline. Japanese clients working with experienced intermediaries who understand both systems navigate this much more efficiently than those applying directly.
Radar chart showing compliance burden dimensions: US clients score highest on regulatory reporting complexity (FATCA/FBAR); Chinese clients score highest on capital controls and AML risk tier; Japanese clients score highest on documentation translation requirements; Canadian clients score moderately on cross-border reporting overlap. All groups score similarly on standard KYC requirements.
Why Non-CRS Countries Create the Hardest Cases
This is the most misunderstood factor in Swiss banking for non-residents, and it deserves a full explanation.
The Common Reporting Standard (CRS) is a global framework where participating countries automatically exchange financial account information with each other. Switzerland exchanges data with 108 partner jurisdictions as of 2024. When you are a tax resident in a CRS country, Swiss banks can be confident that your account will be reported to your home tax authority — and therefore that you are in the system. They know the rules. The compliance framework is predictable.
When a client is domiciled in a non-CRS country — think parts of the Gulf, certain Caribbean jurisdictions, or nations that have not yet implemented CRS — Swiss banks face a fundamental problem: there is no automatic reporting mechanism, and therefore no way to verify tax compliance through standard information exchange channels. The bank must independently verify tax status. This requires manual investigation, third-party tax verification, and often a formal tax opinion from the client’s home country. This is expensive, time-consuming, and creates ongoing liability for the bank if the client later proves to have been non-compliant.
“Swiss banks do not dislike non-CRS clients because they assume they are dishonest. They dislike them because the compliance infrastructure to serve them properly simply does not exist in the same automated way. Every non-CRS client is a custom compliance project. Not every bank wants to take that on.”
In practice, non-CRS domiciled clients have two realistic pathways to Swiss banking. First, they can approach mid-market private banks that have built specific compliance frameworks for their region — certain Swiss banks actively serve Gulf clients, for example, and have dedicated Middle East relationship teams. Second, they can engage a professional intermediary who understands how to structure the application to satisfy the bank’s manual verification requirements. Coming in cold, without preparation, almost never works for non-CRS clients at the private banking level.
It is also worth noting that from 2026, Switzerland’s CRS reporting will expand to include crypto-asset data under the Crypto-Asset Reporting Framework (CARF). The first exchange will occur in 2027 with 74 partner jurisdictions. This adds another dimension to consider for clients with significant digital asset holdings.
Who Cannot Open a Swiss Bank Account — The Clear Lines
Some of the restrictions here are absolute. Others are more nuanced. Let me be specific about each category, because I have seen clients surprised by rules they did not know existed.
Sanctioned Individuals and Entities
This is the hardest line. Swiss banks screen every applicant against multiple sanctions lists: the SECO (State Secretariat for Economic Affairs) list, which is Switzerland’s primary domestic sanctions register; the EU consolidated sanctions list; the US OFAC SDN list; and the UN Security Council consolidated list. If you appear on any of these lists, no Swiss bank — regardless of size or approach — can open an account for you. This is not a compliance policy choice. It is a legal prohibition under Swiss law and international treaty obligations.
Switzerland has implemented significant sanctions against Russia since 2022. The legal prohibition for Russian nationals is now specific and sweeping: deposits exceeding CHF 100,000 are prohibited for Russian citizens unless they hold a Swiss or EU residence permit or dual citizenship. UBS, following the Credit Suisse acquisition, has implemented additional policies requiring Russian clients to demonstrate Swiss residence or citizenship to maintain accounts. Banks that continue to serve sanctioned individuals face FINMA enforcement action and criminal liability for responsible officers.
Beyond Russia, Switzerland implements EU sanctions against Belarus, Myanmar, Iran, North Korea, Syria, and other designated jurisdictions. If you have a nationality from a sanctioned country, or if your business activities connect you to a sanctioned entity, you should obtain a legal opinion before approaching any Swiss institution.
Politically Exposed Persons (PEPs)
PEPs are not automatically excluded — but the standard changes dramatically. Any current or former holder of a prominent public function (heads of state, senior government officials, senior judiciary, senior military, senior executives of state-owned enterprises, and their immediate family members or known associates) triggers EDD as a minimum requirement. Some Swiss banks simply decline all PEPs as a risk policy. Others will proceed, but only with senior management approval, extensive documentation, and minimum deposit thresholds well above standard. If you believe you may be classified as a PEP or PEP-adjacent, flag this proactively. Trying to obscure PEP status always ends worse than disclosing it.
Clients with Financial Crime History
Swiss banks conduct adverse media screening and criminal record verification. Convictions for financial crimes — fraud, money laundering, tax evasion, corruption — are grounds for automatic rejection. Swiss banks are also increasingly screening for civil judgments and regulatory enforcement actions from other jurisdictions. The scope here has widened significantly since 2020.
Clients Whose Activity Violates Swiss Law
If your intended account purpose involves activities prohibited under Swiss law — financing terrorism, arms dealing without SECO authorization, narcotics-related trade, or human trafficking — the application will be rejected and reported to MROS (Money Reporting Office Switzerland). This is not the grey area it might seem: Swiss compliance officers are trained to identify purpose-of-account risk, and they ask direct questions about intended account use.
Clients Who Cannot Document Their Source of Wealth
This one surprises people. You can be a completely legitimate, fully law-abiding individual with genuine wealth — and still be declined if you cannot document where that wealth came from. I have seen this with clients who built successful cash businesses, clients who received wealth through informal inheritance arrangements, and entrepreneurs whose early business records simply no longer exist. The burden of documentation is on the client. “I built a successful business” is not documentation. Audited financials, tax records, and transaction trails are documentation.
For foreign clients who want to understand the full account opening process from first contact to approval, our guide on opening a bank account as a non-resident covers the process in detail.
A Real Case: What Getting It Right Looks Like
I want to share a real case from 2025 — anonymized, but accurate in its structure — because it illustrates the gap between a prepared and unprepared application better than any checklist can.
The client was an IT entrepreneur from Central Asia with a clean but complex financial history: income spread across three jurisdictions, a Cayman holding structure, and a CIS nationality that put him in EDD territory automatically. He had been rejected by two Swiss banks before he came to us. Both rejections cited “insufficient documentation” — the standard phrasing banks use when they cannot close the gaps in your file.
We spent six weeks before approaching any bank. We rebuilt his wealth timeline from incorporation to present day, cross-referenced against tax filings in each jurisdiction, resolved an inconsistency in corporate revenue figures between two documents from the same period, and wrote a 14-page business explanation memorandum that pre-empted every question the compliance team would ask. We selected a mid-market Swiss private bank with an established Central Asian compliance framework rather than approaching a brand-name institution that had no infrastructure for his profile.
The application was approved in eight weeks. The client was the same person. The assets were the same. What changed was the story the bank’s compliance team received — and how easy we made it for them to document it.
The lesson I return to every time: Swiss banks do not reject good clients. They reject unclear stories. Your wealth is not the application. Your documented, consistent, chronologically logical financial narrative is the application.
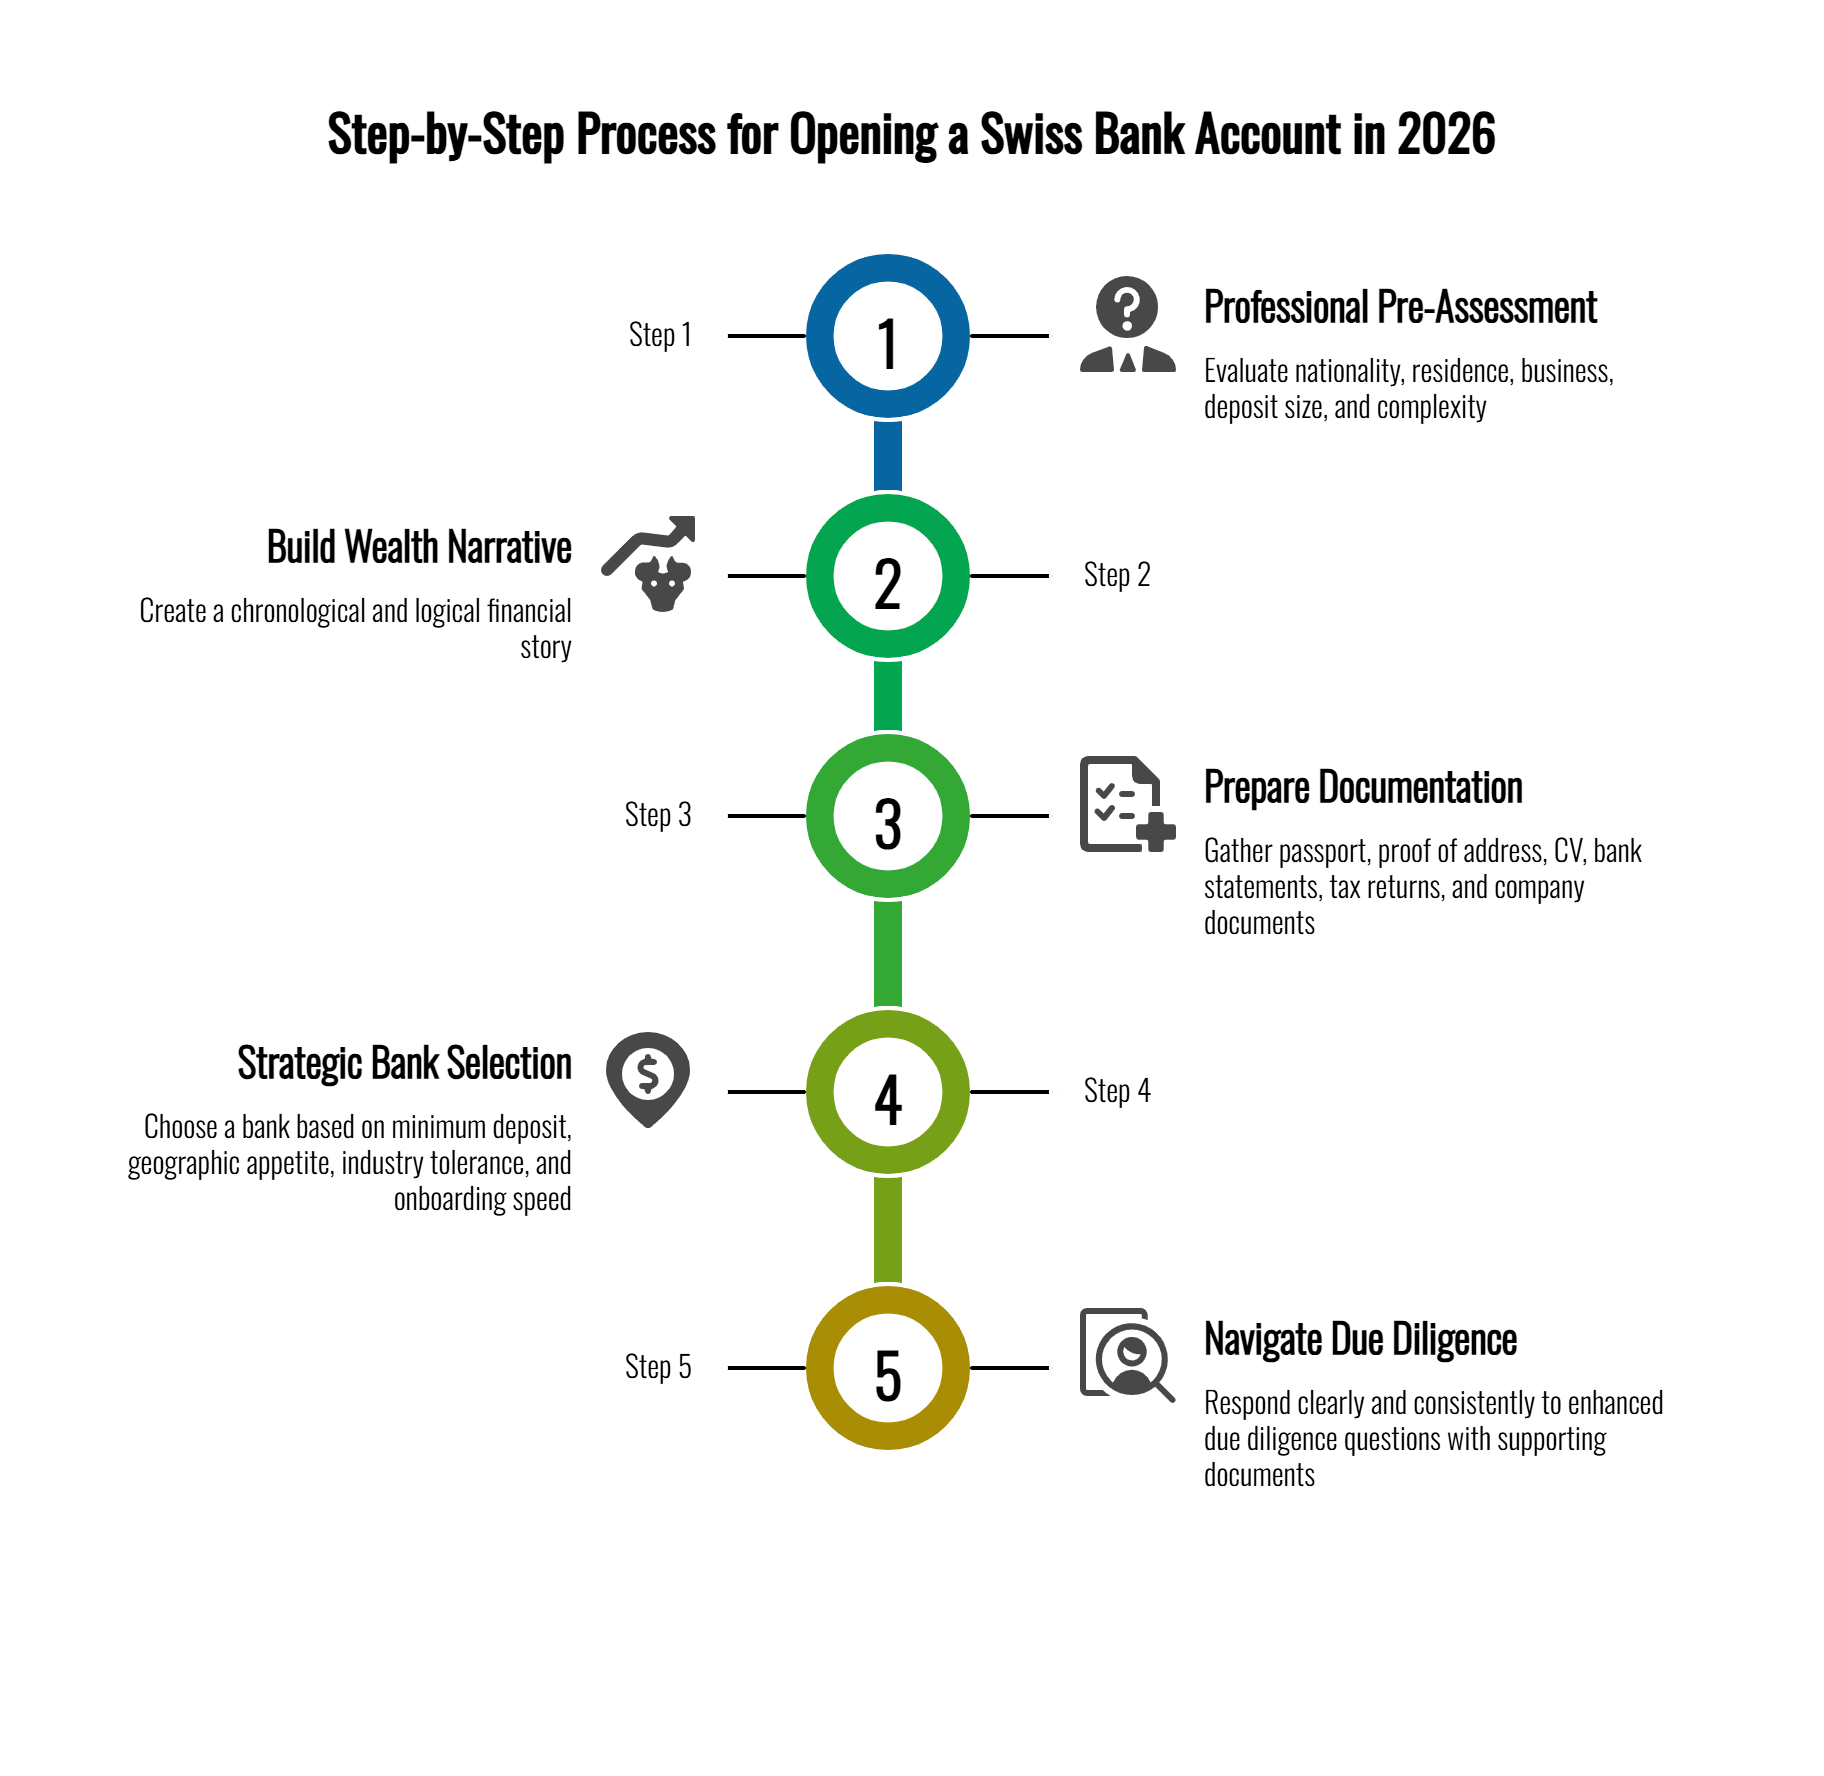
The Strategic Steps That Actually Work in 2026
After years of working alongside compliance teams — and against them on behalf of clients — this is the process that produces consistent results.
Step 1: Honest Self-Assessment Before Anything Else
Before you contact a single bank, evaluate your risk profile honestly. What is your nationality? What is your tax residence? Does your business activity fall into any of the elevated-scrutiny categories? Where did your wealth come from, and how thoroughly can you document it? Can you explain every significant deposit or receipt over the past decade? The answers to these questions determine your viable bank universe. Skipping this step and applying to the wrong bank is the most expensive mistake in Swiss banking — it costs you time, rejection records, and sometimes the ability to apply to other banks in the near term.
Step 2: Build Your Wealth Narrative First
This means creating a chronological, documented account of how your wealth accumulated. Starting from your first income, through your business growth, through asset accumulation. Every tax payment should be traceable. Every significant transaction should have a documented counterparty. Every corporate structure should have a clear, logical rationale. This is not something you put together the week you apply. For complex profiles, this takes four to eight weeks to build properly.
Step 3: Match Your Profile to the Right Bank
Swiss banks have dramatically different appetite for different client profiles. A bank that actively courts Gulf clients may have no infrastructure for East Asian clients. A bank that is experienced with US FATCA clients may not have a Central Asian compliance framework. Random applications are expensive mistakes. Strategic matching is how successful applications get filed. At BMA Business Solutions, this bank selection process — matching your specific risk profile to institutions with the right compliance history — is often the most important thing we do for clients. To understand how Swiss company registration intersects with banking requirements, our company registration guide covers the corporate banking path specifically.
Step 4: Prepare Documentation to EDD Standard
Even if you think you will only face standard KYC, prepare everything to Enhanced Due Diligence quality. This means notarized translations where required, apostilled corporate documents, cross-referenced tax records that are internally consistent, a professional CV, and a bank introduction letter if you have existing relationships with reputable institutions. Over-prepared applications almost never slow down. Under-prepared applications almost always do.
Step 5: Support the Bank’s Compliance Process
Once your file is submitted, your job is to answer questions quickly, completely, and consistently. Every delay in responding to a compliance request extends your timeline. Every vague answer generates another question. Every inconsistency triggers a deeper review. Banks are not adversaries here — they are trying to build a compliant file. Help them do that.
Key Facts: Swiss Banking in Numbers (2026)
| Metric | Figure | Source / Context |
|---|---|---|
| Total assets under management at Swiss-based banks | CHF 9,284 billion (CHF 9.284 trillion) | Swiss Banking Association, Banking Barometer 2025 — all-time high, end-2024 |
| Share belonging to foreign-domiciled clients | 45.5% (CHF ~4.2 trillion) | Swiss Banking Association, Banking Barometer 2025; down from 51.1% in 2014 due to CHF strengthening |
| Cross-border private client wealth (Swiss banks as global leader) | CHF 2,427 billion — 25% of global cross-border | Swiss Banking Association, Banking Barometer 2025; up 10.0% year-on-year (currency-adjusted) |
| CRS partner jurisdictions (Switzerland) | 108 countries | SIF, 2024; CARF (crypto) from 2027 |
| Deposit protection (esisuisse) | CHF 100,000 per client per bank | Applies automatically; covers CHF + foreign currency |
| Typical compliance timeline (non-resident) | 4–8 weeks standard; 8–16 weeks EDD | Based on BMA Business Solutions client data |
| New Swiss account openings via fintech/online (last 5 years) | ~90% of all new international openings | Industry observation, Goldblum and Partners 2026 |
| Julius Baer minimum (post Dec 2025 tightening) | CHF 1,000,000+ | Julius Baer client communication, Dec 2025 |
If your goal involves setting up a Swiss legal entity alongside your banking relationship — which often significantly improves the onboarding profile — our guide on how to open a company in Switzerland as a foreigner walks through the registration pathway and how it interacts with bank account requirements.
Corporate Account Opening: What Businesses Need
Corporate accounts are a separate world from personal banking — and a dimension where many foreign clients are genuinely surprised by the requirements. The compliance logic is identical, but the documentation burden is roughly double. Banks are not just screening you as an individual; they are screening your entire corporate structure, its beneficial owners, its transaction logic, and its economic substance in Switzerland or elsewhere.
In my experience, corporate account rejections happen most often not because the business is problematic, but because the documentation package fails to tell a coherent story about what the company actually does and why it needs a Swiss bank account. Every document needs to connect to every other document. A mismatch between the stated business model and the financial statements — even a minor one — triggers a detailed investigation.
Personal Documents Required (All Directors and UBOs)
| Document | Specification | Notes |
|---|---|---|
| Passport (certified copy) | Valid; notarised or apostilled | Apostille required for non-EU jurisdictions in most cases |
| Proof of residential address | Utility bill or bank statement ≤3 months old | Must show full name and address; mobile bills usually rejected |
| CV / professional biography | Detailed career history | Banks verify this against LinkedIn and public records |
| Tax identification number (TIN) | From country of tax residence | Mandatory for CRS reporting |
| Source of wealth declaration | Personal narrative + supporting documents | Tax returns, business ownership proof, sale agreements |
| PEP declaration | Signed self-declaration | Must cover immediate family members; false declaration = account closure |
Corporate Documents Required
| Document | Specification | Notes |
|---|---|---|
| Certificate of incorporation | Official government-issued; apostilled | Must be current or accompanied by good standing cert |
| Articles of association / statutes | Full constitutional documents | Banks read these; inconsistencies between stated purpose and activity are flagged |
| Commercial register extract | Not older than 12 months | Shows directors, capital, registered address |
| Good standing certificate | Not older than 3 months (for companies >6 months old) | Required by almost all Swiss private banks |
| Shareholder register | Full chain to Ultimate Beneficial Owner (UBO) | Must reach a natural person; no anonymous ownership permitted |
| UBO declaration (Form A / Form K) | FINMA-standard beneficial ownership forms | Form A for direct beneficial owners; Form K for dominating persons in foundations/trusts |
| Management body certificate | Current directors; not older than 12 months | Some banks require notarised version |
| Corporate tax identification number | TIN from jurisdiction of incorporation | Required for CRS corporate reporting |
| Financial statements (last 2 fiscal years) | Audited preferred; management accounts acceptable for newer companies | Revenue figures must align with bank statements submitted |
| Bank statements (last 6–12 months) | All active business accounts | Shows actual transaction flows; must match stated business model |
| Business description memorandum | Explains business model, client base, geographic footprint, expected Swiss transactions | This is the single most important document. Generic descriptions fail. |
| Key client / counterparty contracts | Representative samples | Must substantiate stated revenue level |
| Expected account activity | Estimated monthly turnover, transaction corridors, currencies | Mismatches between stated and actual flows trigger retrospective review |
Corporate minimum deposits for foreign entities range from CHF 10,000 to CHF 100,000 at the lower end, rising to CHF 500,000 and above at established Swiss private banks. The specific threshold depends heavily on the jurisdiction of incorporation. A UK-registered company with full audited accounts faces a very different process from a Cayman or BVI entity — not because either is inherently problematic, but because the compliance infrastructure to verify offshore structures is more resource-intensive for the bank.
“One thing I always tell corporate clients: your business description memorandum is not an afterthought. It is the compliance officer’s primary reference document. I have seen complete, accurate, perfectly notarised document packages declined because the one-paragraph business description was vague. I have also seen complex, multi-jurisdictional structures approved because the narrative was precise enough that the compliance team could close their file confidently.”
What You Will Actually Pay: Swiss Banking Fees Explained
Opening the account is one cost. Running it is another — and the second one surprises more clients than the first. Swiss bank fees are not one number. They are a layered structure that changes depending on which service model you choose. Understanding this before you open is not optional if you want to manage your total cost of banking.
The Three Service Models and What Each Costs
Swiss private banks offer three distinct mandates. Which one you select determines your entire fee architecture.
Under an execution-only mandate, you make all investment decisions and the bank executes them. You pay per transaction, plus account maintenance and custody fees. The appeal is control; the risk is cost unpredictability if you trade frequently.
An investment advisory mandate adds a layer of bank research, formal recommendations, and portfolio monitoring — but you still approve every trade. Advisory fees of 0.15% to 0.25% annually are added on top of standard transaction and custody costs.
A discretionary mandate delegates all day-to-day investment decisions to the bank within an agreed strategy. The bank charges 1% to 2% annually, which in an all-in model typically includes custody, maintenance, and trading costs. For busy executives and internationally mobile clients who do not want active portfolio oversight, this is the cleanest structure.
Grouped bar chart showing four scenarios for a CHF 5 million portfolio. Execution-only standard fees: CHF 53,500–59,500. Advisory standard fees: CHF 49,000–56,000. Discretionary all-in at 1.2%: CHF 60,000. Discretionary standard fees: CHF 75,000–80,000. All-in discretionary and advisory are the most cost-effective options.
| Fee Type | Rate / Amount | Applies To | Practical Impact (CHF 5M portfolio) |
|---|---|---|---|
| Account maintenance | CHF 100–5,000 per year | All accounts | CHF 500–2,000 typically; higher for complex/corporate accounts |
| Securities custody | 0.35%–0.5% per year on portfolio | All securities holdings | CHF 17,500–25,000 on CHF 5M securities — the largest hidden cost |
| Equity transaction commission | 0.5%–2.0% per transaction | Execution and advisory mandates | CHF 1,000 on a CHF 100,000 trade at 1.0% |
| Bond transaction commission | 0.35%–1.0% per transaction | Execution and advisory mandates | CHF 350–1,000 on a CHF 100,000 bond trade |
| Investment advisory fee | 0.15%–0.25% per year | Advisory mandates only | CHF 7,500–11,250 on CHF 4.5M in securities |
| Discretionary management (all-in) | 0.8%–1.6% per year | Discretionary mandates | CHF 40,000–80,000 fully inclusive; no transaction surprises |
| FX conversion | ~0.05%, capped ~CHF 500 | All currency exchanges | CHF 500 cap hit on conversions above CHF 1 million |
| Swiss stamp duty (domestic) | 0.075% per transaction (your share) | Swiss securities purchases/sales | CHF 750 on a CHF 1M Swiss equity purchase |
| Swiss stamp duty (foreign) | 0.15% per transaction (your share) | Foreign securities purchases/sales | CHF 1,500 on a CHF 1M foreign equity purchase |
| EDD / high-risk compliance fee | CHF 500–1,000 per quarter | High-risk classified clients | CHF 2,000–4,000 per year; charged independently of mandate type |
| Account closure fee | CHF 300–500 | On account termination | Sometimes waived for large relationship transfers |
The EDD fee deserves specific attention because it catches non-EU clients off guard. If your profile is classified as high-risk — based on nationality, jurisdiction, business complexity, or PEP adjacency — you will pay CHF 2,000 to CHF 4,000 per year simply for the bank to maintain your compliance file. This is on top of all other charges. It is a legitimate regulatory cost but one that rarely appears in bank marketing materials.
Fee Negotiation: What Is Actually Achievable
Swiss banks do negotiate, more than most people realise. The leverage point is your deposit size. At CHF 5–10 million, expect 10–15% off published rates if you ask directly. At CHF 10–20 million, 15–25% is realistic. Above CHF 20 million, custom pricing applies and significant discounts are standard. Bundling services — advisory, custody, and account management with one institution — also gives negotiating weight. The key is to ask before signing, not after. Once you are onboarded, leverage diminishes considerably.
Tax Considerations for Foreign Clients of Swiss Banks
Tax is where the conversation about Swiss banking often gets oversimplified. On one side, people assume Swiss accounts provide automatic tax advantages. On the other, people assume CRS means everything is reported and there is no point structuring carefully. Neither is accurate. The reality is more specific — and more useful.
Swiss Withholding Tax: The 35% Starting Point
Switzerland levies a 35% withholding tax on interest income from Swiss bank deposits and dividends from Swiss-domiciled companies. This applies automatically at source. For a non-resident client, this is not necessarily a permanent cost — but managing it requires action. Switzerland’s network of Double Taxation Agreements (DTAs) with over 100 countries allows partial or full reclaim of this tax.
A German resident, for example, can reduce withholding to 15% under the Switzerland-Germany DTA. A UAE resident receiving dividends from a US stock held in their Swiss account faces a 30% US withholding tax — because the UAE has no DTA with the US — regardless of where the account is held. Tax outcomes depend entirely on the specific treaty network applicable to your country of residence, not on the location of the bank alone.
Fiduciary deposits offer an alternative route. Under this structure, your Swiss bank invests funds in external jurisdictions as a trustee, generating interest income outside Switzerland. This can avoid Swiss withholding tax entirely — but adds fees and regulatory complexity. It is a tool worth knowing about, not a default solution.
Securities Transfer Tax (Stamp Duty) as a Trading Cost
Every securities transaction through a Swiss bank attracts stamp duty. The rates are 0.075% on Swiss securities and 0.15% on foreign securities per transaction. Both buyer and seller share the tax, so you pay approximately half each way. Bonds and money market ETFs are included — a detail many active traders miss. On a portfolio with moderate annual turnover, stamp duty accumulates to a meaningful figure. Long-term investors are largely unaffected; active traders need to model this cost explicitly.
FATCA, CRS, and CARF: The Reporting Architecture
From 2017, Swiss banks report all non-resident account holders to their respective tax authorities under CRS, covering 108 jurisdictions. From 2027, crypto-asset holdings will be included under the Crypto-Asset Reporting Framework (CARF). US clients face FATCA reporting to the IRS regardless of CRS participation. The practical implication: your Swiss bank account is known to your home tax authority. The benefit of Swiss banking is stability, asset protection, and access to global investment markets — not secrecy from tax authorities. Any consultant suggesting otherwise is wrong and potentially exposing you to serious liability.
| Tax / Obligation | Rate / Mechanism | Who It Affects | Key Action |
|---|---|---|---|
| Swiss withholding tax (interest) | 35% at source | All clients receiving Swiss interest income | Claim reduction via applicable DTA; or use fiduciary deposits |
| Swiss withholding tax (Swiss dividends) | 35% at source | Clients holding Swiss equities | DTA reclaim from home tax authority |
| US withholding on US dividends (no DTA) | 30% | Non-US clients from no-DTA countries (e.g. UAE residents) | Seek tax advice on treaty-eligible structures |
| Swiss stamp duty (domestic securities) | 0.075% per trade (your share) | All trading accounts | Factor into trading frequency decisions; bonds included |
| Swiss stamp duty (foreign securities) | 0.15% per trade (your share) | All trading accounts | Long-hold strategies significantly reduce impact |
| CRS automatic reporting | Annual; 108 countries | All non-Swiss resident clients | Declare account and income in home jurisdiction; non-disclosure = penalties |
| FATCA reporting (US persons) | Annual to IRS | US citizens and US tax residents globally | Annual FBAR filing to FinCEN; declare on US tax return |
| CARF (crypto assets) | Reporting from 2027; 74 jurisdictions | Clients with crypto assets at Swiss banks | Ensure crypto holdings are declared in home jurisdiction from 2027 |
For a practical deep-dive into structuring your Swiss banking relationship tax-efficiently — including DTA strategies and fiduciary deposit structures — the tax considerations guide at Easy Global Banking (opens in new tab) covers each mechanism with worked examples.
FinSA Client Classification: Which Category Are You?
Most foreign clients who open Swiss accounts do not know they have been formally classified under the Financial Services Act (FinSA). This matters — significantly — because your classification determines which investment products you can access, what protections apply, and how your bank structures its advisory relationship with you.
FinSA, which came into force in 2020, creates three distinct client tiers. It is not bureaucratic box-ticking. The tier you fall into determines whether you can access complex structured products, derivatives, and non-registered funds — or whether you are limited to standard instruments. For wealthy non-residents seeking sophisticated portfolio strategies, understanding this and knowing how to change it is a genuine strategic lever.
The Three FinSA Tiers
Private (Retail) clients is the default classification. If you have not explicitly opted out, you are here. Swiss banks are required to conduct full suitability assessments before recommending any investment, provide Key Information Documents (KIDs) for complex products, and document every recommendation. Protection is strong. But access is limited — derivatives, leveraged products, non-registered collective investment schemes, and complex structured instruments are unavailable to retail clients.
Professional clients is the tier most internationally active HNWIs should explore. You qualify automatically if you are a large company (exceeding two of: CHF 20M balance sheet, CHF 40M revenue, CHF 2M equity), a pension fund with professional treasury operations, or a regulated financial intermediary. As an individual, you can opt out to professional status — gaining access to the full investment universe — if you meet either of these thresholds: CHF 500,000 in eligible assets plus demonstrable professional financial knowledge or experience, OR CHF 2,000,000 in eligible assets with no expertise requirement. Note: eligible assets include bank deposits, securities, and collective investment units — but explicitly exclude real estate, pensions, and social security entitlements.
Institutional clients receive minimal regulatory protection because they are assumed to be fully capable of independent analysis. Banks, insurance companies, fund managers, and large regulated entities fall here. Most private clients do not reach this tier and do not need to.
| Classification | Default Qualification | Protection Level | Investment Access | Opt-Out / Opt-In Criteria |
|---|---|---|---|---|
| Private (Retail) | All individuals by default unless reclassified | Maximum — suitability assessment required; KID provided | Standard: equities, bonds, UCITS funds — no complex instruments | Can opt out to Professional if CHF 500k + experience, or CHF 2M assets |
| Professional | Large companies, pension funds, regulated intermediaries; or individuals who opt out | Reduced — appropriateness check only; conduct rules can be waived by written agreement | Broad: structured products, derivatives, non-registered funds, alternative investments | Individuals: CHF 500k eligible assets + financial expertise, OR CHF 2M eligible assets (no expertise needed) |
| Institutional | Banks, insurers, fund managers, central banks, supranationals | Minimal — counterparty relationship; most FinSA conduct rules do not apply | Unrestricted access to all financial instruments | Some professional clients (large corporates, pension funds) can opt in by written declaration |
There is one more layer that matters specifically for fund access: CISA qualified investor status under the Collective Investment Schemes Act. Professional and institutional clients automatically qualify. Retail clients only qualify if they hold an active advisory or discretionary mandate with a regulated intermediary. Without CISA qualified investor status, a retail client cannot invest in “qualified investor funds” — a fast-growing category of performance-oriented vehicles — regardless of how wealthy they are. This is a specific, practical reason why retail classification is not always appropriate for high-net-worth foreign clients.
The process for requesting a classification change takes approximately two to three weeks and requires written application with documentation. Once classified, it applies across all services with that provider — you cannot be retail for equities and professional for derivatives. For foreign clients who intend to pursue active portfolio strategies from day one, I recommend addressing classification during the account opening process rather than retroactively. For a full technical breakdown of the FinSA framework and how to navigate it, the FinSA client classification guide at Easy Global Banking (opens in new tab) is the most comprehensive resource I have seen that is written specifically for international clients.
Frequently Asked Questions (FAQ)
What is the realistic minimum deposit for a non-resident foreigner at a Swiss private bank in 2026?
Can a US citizen open a Swiss bank account?
What is Enhanced Due Diligence (EDD) and when does it apply?
Why is it harder to open a Swiss bank account if I live in a non-CRS country?
Does Switzerland participate in the automatic exchange of financial information?
Can I open a Swiss bank account remotely as a non-resident?
Who absolutely cannot open a Swiss bank account?
References
- State Secretariat for International Financial Matters (SIF) — Automatic Exchange of Information (AEOI) (opens in new tab)
- FINMA — Banks and Securities Firms Supervision Framework (opens in new tab)
- SECO — Swiss Sanctions and Embargoes Register (opens in new tab)
- Swiss Banking Association — Compliance and Regulatory Framework (opens in new tab)
- Easy Global Banking — Swiss Bank Fees for Private Clients: Complete 2026 Guide (opens in new tab)
- Easy Global Banking — Tax Considerations for Clients of Swiss Banks (opens in new tab)
- Easy Global Banking — FinSA Client Classification Guide for International Investors (opens in new tab)